US Equity Daily: Broad benchmarks retain a constructive bias (2026-09-18)
An evidence-led assessment of US equity direction, participation, volatility and option inventory across major index proxies and the most active verified names.
Our base case is constructive, with 65% confidence. QQQ, SPY and DIA show an average one-day move of +1.20%, a five-session move of +0.49%, and a one-month move of -1.19%. The tape is in a quiet regime, with average 20-day realized volatility of 11.7%.
The conclusion comes from breadth, not from the strongest single ticker: 1 of 3 available benchmark proxies are positive over one month and 2 are negative. That alignment supports risk appetite, although the volatility regime still determines how much confidence to place in the move.
- Published
- September 18, 2026
- Updated
- September 18, 2026
- Author
- heidegger_softstrong
- Topic Hub
- US Equity Options
- Reading time
- 8 min read
- Report type
- US Equity Daily Strategy Note
- Market stance
- long (65%)
Our base case is constructive, with 65% confidence. QQQ, SPY and DIA show an average one-day move of +1.20%, a five-session move of +0.49%, and a one-month move of -1.19%. The tape is in a quiet regime, with average 20-day realized volatility of 11.7%.
The conclusion comes from breadth, not from the strongest single ticker: 1 of 3 available benchmark proxies are positive over one month and 2 are negative. That alignment supports risk appetite, although the volatility regime still determines how much confidence to place in the move.
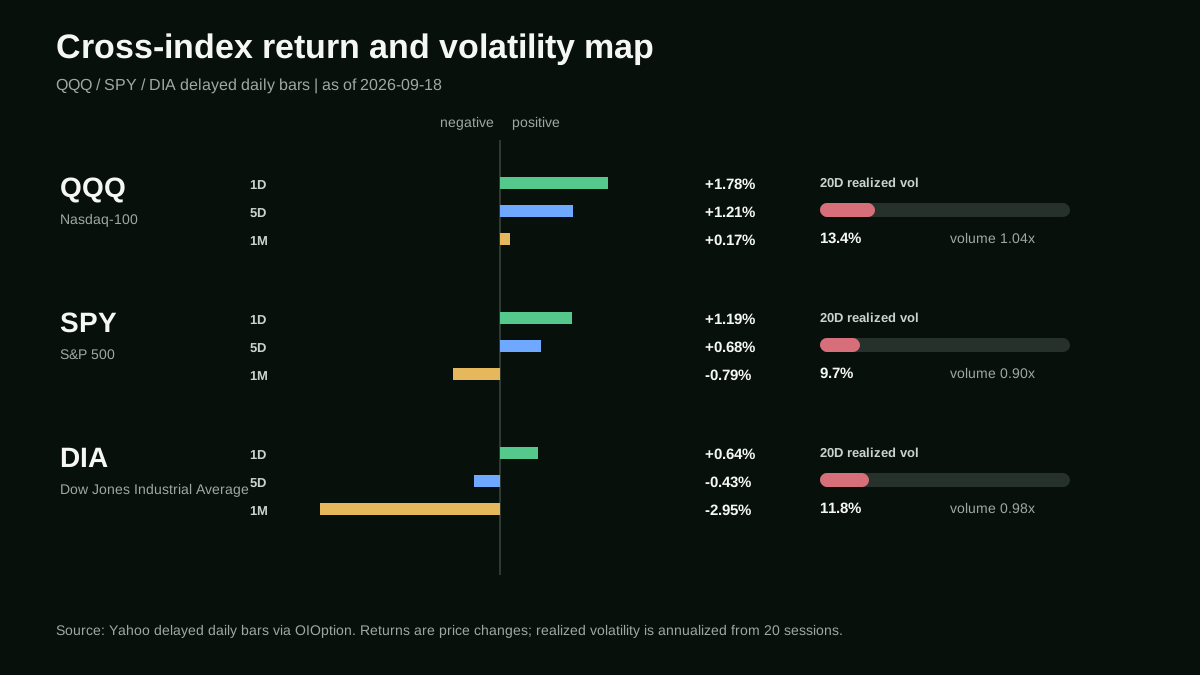
QQQ, SPY and DIA returns across three horizons with 20-day realized volatility and participation.
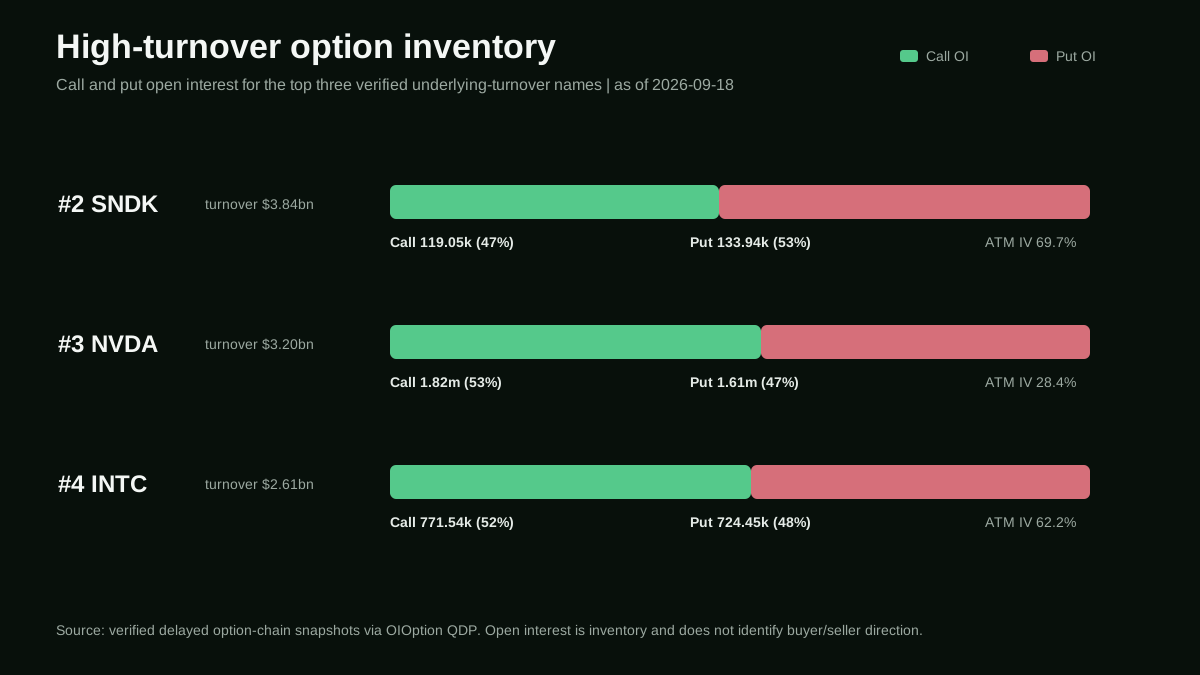
Call/put open-interest composition for the three highest-turnover verified option underlyings.
Investment view
Evidence is ranked deliberately: cross-index price breadth determines direction; realized volatility and volume determine the quality of that direction; option inventory measures where participation is concentrated; news supplies testable context. A lower-ranked input cannot overrule a contradictory higher-ranked signal.
Data cutoff: benchmark bars are observed through 2026-09-17T13:30:00Z; option inventory is observed through 2026-09-17T19:59:01.636197539Z. Both are delayed reference snapshots, and the publication date must not be read as a live quote timestamp.
The evidence behind the view
We treat QQQ, SPY and DIA as liquid proxies for growth, the broad large-cap market and industrial/value exposure. Agreement among them is stronger evidence than a move concentrated in one index.
QQQ (Nasdaq-100) closed at $717.27: +1.78% over one day, +1.21% over five sessions and +0.17% over one month. Realized volatility is 13.4%; latest volume is 1.04x of its 20-day average. The weekly and monthly horizons confirm each other, so the trend evidence is positive rather than merely intraday.
SPY (S&P 500) closed at $763.02: +1.19% over one day, +0.68% over five sessions and -0.79% over one month. Realized volatility is 9.7%; latest volume is 0.90x of its 20-day average. The horizons disagree, so this proxy is a source of dispersion rather than confirmation.
DIA (Dow Jones Industrial Average) closed at $518.51: +0.64% over one day, -0.43% over five sessions and -2.95% over one month. Realized volatility is 11.8%; latest volume is 0.98x of its 20-day average. The weekly and monthly horizons confirm each other on the downside, which makes a one-day bounce insufficient to reverse the signal.
Options activity: participation, not a directional vote
The three highest-turnover verified option underlyings are SNDK, NVDA, INTC. Their combined chain contains 3700 contracts, 2.70m contracts of reported session volume and 5.17m contracts of open interest. Aggregate inventory is two-sided, but open interest cannot reveal whether options were bought or sold; it measures where exposure exists, not the sign of the trade.
#1 SNDK: underlying turnover $3.84bn; spot $1,530.90; one-day / five-session / one-month returns -1.36% / -11.92% / -14.32%. The verified chain contains 1842 rows with call/put open interest of 119.05k / 133.94k (47.1% calls) and ATM IV of 69.7%. The snapshot is 2.5h old. Price sits between or close to the two moving averages, leaving trend confirmation incomplete.
#2 NVDA: underlying turnover $3.20bn; spot $213.90; one-day / five-session / one-month returns +0.82% / -4.37% / -2.66%. The verified chain contains 952 rows with call/put open interest of 1.82m / 1.61m (53.1% calls) and ATM IV of 28.4%. The snapshot is 2.5h old. Price sits between or close to the two moving averages, leaving trend confirmation incomplete.
#3 INTC: underlying turnover $2.61bn; spot $101.05; one-day / five-session / one-month returns +4.03% / -4.89% / +4.51%. The verified chain contains 906 rows with call/put open interest of 771.54k / 724.45k (51.6% calls) and ATM IV of 62.2%. The snapshot is 2.5h old. Price is above both the 20- and 50-day averages, so option activity is occurring inside a positive trend structure.
One or more active names did not return a fresh Yahoo daily bar after bounded retries. The report uses the latest persisted bar when available and labels unavailable fields as n/a; option inventory and benchmark evidence remain independently sourced.
Event and news context
News is used as context, not as a retroactive explanation for every price move. The following recent items can affect discount rates, index earnings expectations or active names in this report; causality still requires confirmation in price, breadth and volatility.
- -No current qualifying news items were available from the configured public sources at the publication cutoff. The market and option evidence above remains usable; this section is intentionally left without an invented headline.
Scenario map and conclusion
Base case: retain the constructive assessment until at least two benchmark proxies establish a common five-session direction inconsistent with the aggregate view. The present reading is a market-state assessment, not a price target.
Upside confirmation requires at least two of QQQ, SPY and DIA to remain positive over five sessions while volume participation moves toward or above the 20-day norm. That combination would show breadth and participation reinforcing price.
Downside confirmation requires at least two proxies to turn negative over five sessions alongside rising realized volatility. For the active names, breaks below the observed 20-session ranges (SNDK $1,416.56, NVDA $207.25, INTC $85.14) would add company-level evidence, but would not alone define the index regime.
Conclusion: US equities are constructive, but the signal is conditional on breadth surviving and volatility remaining orderly. The options data supports the participation assessment, while the benchmark complex remains the authority for market direction. The view should change when the cross-index evidence changes, not when one headline or one option strike becomes conspicuous.
Desk conclusion
- -Direction: constructive, supported by 1/3 positive one-month benchmark proxies.
- -Participation: the top-turnover option group is two-sided, but inventory is not treated as a directional flow signal.
- -What changes the view: a common five-session reversal across at least two benchmark proxies, confirmed by volume and realized volatility.
Disclosure
All market and option-chain observations are delayed reference data and may differ from executable prices. This report is informational research, not investment advice or a solicitation.
ETF proxies do not represent every US stock, and option open interest can reflect hedges, spreads, overwriting or stale positions. Conclusions should be updated when source coverage, freshness or cross-index agreement changes.